More Sales or Less Overhead? Run Both Numbers
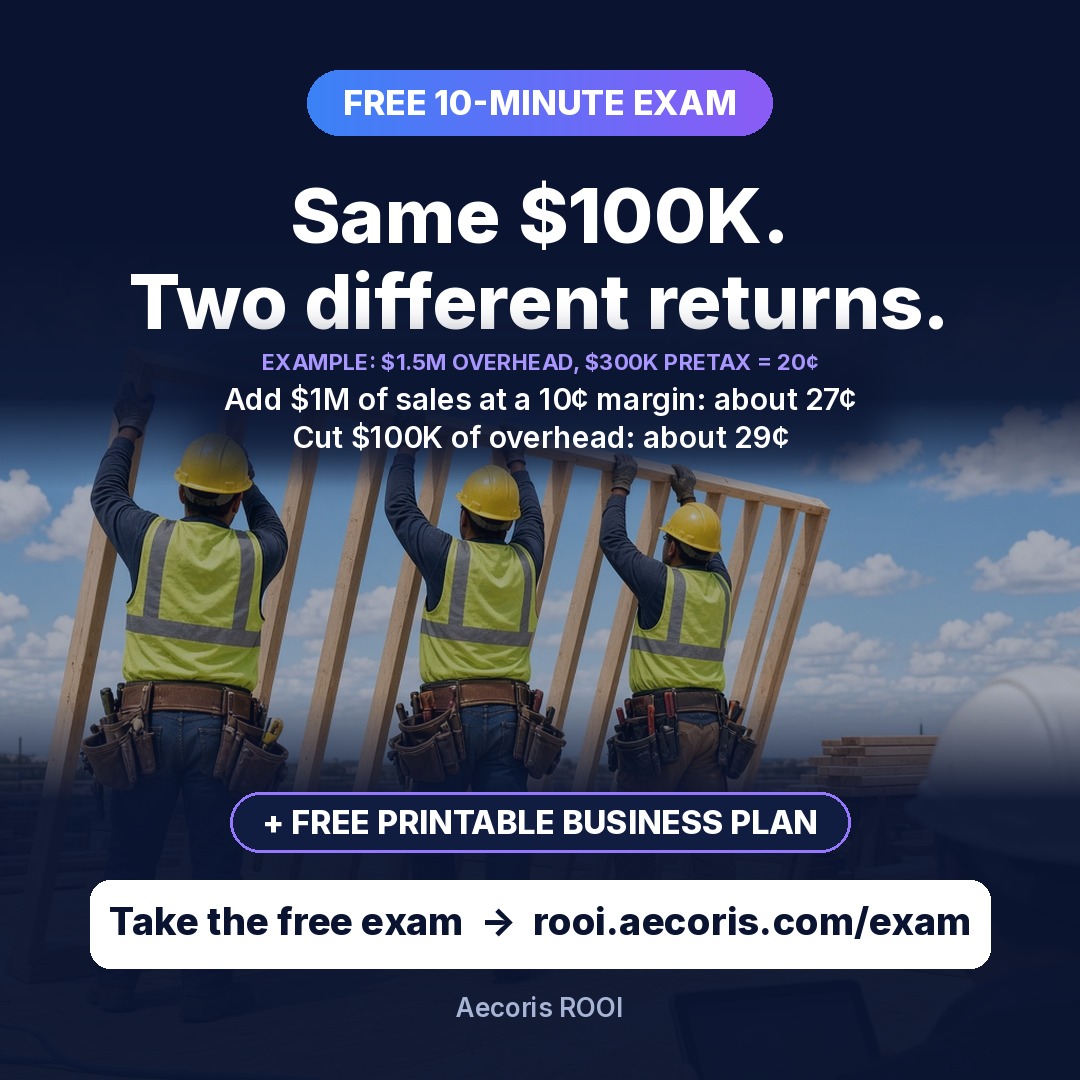
Here's an example. A company carries $1.5 million of overhead and makes $300,000 pretax.
That's 20 cents back on each overhead dollar.
Now the owner wants more profit. Which moves it more: $1 million of new sales, or $100,000 less overhead?
Path one: add sales
Add $1 million of sales at 10 cents of margin, with overhead flat.
That's $100,000 more margin. Pretax goes to $400,000. The return is about 27 cents on $1.5 million of overhead.
Not bad.
Path two: cut overhead
Cut $100,000 of overhead instead. Sales stay where they are.
Pretax also goes to $400,000. But now it's on $1.4 million of overhead. The return is about 29 cents.
Same profit, different company
Same $100,000 of profit. Two different returns.
And the second path also takes less risk, fewer crews and less cash tied up in new work.
Think about what the first path really needs. $1 million of new work has to be estimated, won, staffed and built. Crews have to be found. Cash goes out for payroll and material before the owner pays. Retainage sits on the job. Any of that can go wrong, and the 10 cents of margin can shrink to 5.
The second path needs a decision. Maybe a hard one. But it doesn't need new crews or new cash.
I'm not saying cut
I'm not saying cut. Overhead isn't bad. It's what lets a company run more work, manage it well and grow. Some overhead returns far more than it costs. Read about the three kinds of overhead.
I'm saying run both numbers before you chase volume.
Most owners default to more sales. It's what our industry celebrates. But more sales is often the harder, riskier way to the same profit.
Questions to ask
Before your next push for volume, ask:
- What margin will the new work really carry?
- What overhead is in the budget that isn't earning its keep?
- What would each path do to the return on overhead?
- What does each path need in cash, people and bonding?
- Which path is more likely to actually happen?
Sometimes the answer is sales. Sometimes it's overhead. Sometimes it's both. The point is to choose on purpose.
Watch for the opposite mistake
There's a trap on the other side too. A company that shrinks can see its return go up while the business gets weaker. Read sales went down, our return went up. Cutting overhead works when the overhead wasn't earning anything. It doesn't work when you cut the people who run the work.
Do the math with your own numbers
Take your own overhead and pretax profit. Figure the return. Then run the two paths. What would $1 million of new sales at your real margin do? What would cutting $100,000 of overhead that isn't earning anything do? Put the two returns side by side. The answer may surprise you. When I first did this for my own company, it changed which conversations I had first with my managers.
Either way, you'll be choosing with numbers instead of habit.
Find your number
If you don't know your return on overhead, start there. It's pretax profit divided by overhead. Read what ROOI is.
Then take the free ROOI exam. It asks 20 yes-or-no questions about the systems behind your sales, margin and overhead. You'll see your score against same-size firms, the pretax profit at stake each year and the first step to close each gap. The free planner after it lets you run both numbers for your own company.